

In Lagos, "send me on OPay" or "transfer via USSD" is everyday. Nigeria's 220 million people, a young majority and a ferocious fintech scene — Flutterwave, Paystack, OPay, PalmPay, Kuda, Moniepoint — make it the largest single market in Africa. And the rails to serve it already exist. That is why Nigeria is such natural soil for mini-programs.
The opportunity is not another app to install. It is a lightweight program that rides Nigeria's instant rails (NIP, USSD *901#) inside the wallets Nigerians already use — reaching the underbanked without forcing them through a native-app wall.
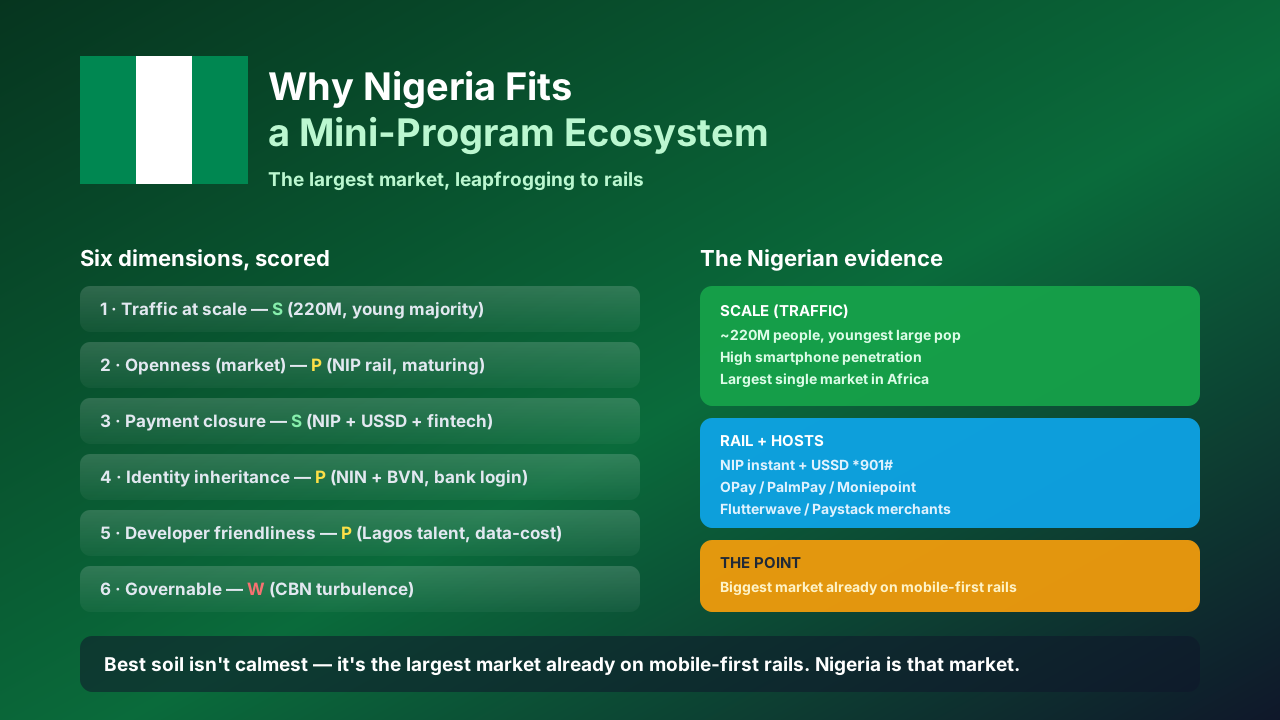
The six dimensions, scored on Nigerian ground
1. Traffic at scale. Nigeria has ~220 million people, the youngest large population on earth, with high smartphone and mobile penetration. A massive daily-attention market.
2. Openness, at the market level. NIBSS Instant Payment (NIP) is a real-time interbank rail open to banks and licensed processors, and USSD *901# brings banking to feature phones. Open in principle — though fragmentation and recent policy turbulence keep adoption maturing.
3. Payment closure. A mini-program inherits NIP plus USSD plus a dense fintech layer (OPay, PalmPay, Moniepoint, Kuda; Flutterwave and Paystack for merchants). Real-time settlement is already widely available.
4. Identity inheritance. This is the moderate link. NIN (National Identity Number) and BVN (Bank Verification Number) form a strong base, but mini-app login still leans on wallet or bank credentials rather than a single universal handoff. Workable, not yet WeChat-class.
5. Developer friendliness. Lagos' "Yabacon Valley" is a deep English-speaking engineering pool, but data costs and app-fatigue among the mass market make lightweight distribution the obviously right call.
6. Governable. This is the weak link. The CBN has pushed cashless policy and instant payments, but recent turbulence — the 2023 cash crunch, FX instability and shifting rules — makes governance the fragile part of an otherwise strong setup.
| Dimension | Score | Nigerian evidence |
|---|---|---|
| Traffic | S | 220M people, young majority |
| Openness | P | NIP instant rail, USSD *901# |
| Payment | S | NIP + USSD + OPay/PalmPay |
| Identity | P | NIN + BVN, bank login |
| Developer ease | P | Lagos talent, data-cost mindful |
| Governance | W | CBN turbulence, cash crunch |
Why "the largest market, leapfrogging to rails" is the point
Nigeria is the biggest single market in Africa, and it is leapfrogging straight to instant, mobile-first rails. Closed hosts (OPay, PalmPay, Moniepoint) plus an open-ish interbank rail (NIP) plus NIN/BVN identity make it prime soil — if you can ride the governance turbulence.
The CrossMiniApp angle
CrossMiniApp is a universal runtime plus an open catalog. You build the mini-program once and it runs inside OPay, PalmPay and Moniepoint surfaces — inheriting each host's identity and payment, sandboxed and governable, updatable over the air. Nigeria's scale-first structure is the argument: the market is enormous, the rails exist, and the value is in a runtime that reaches users without the native-app wall.
The rule
The best soil isn't the calmest — it's the largest market that already leapt to mobile-first rails. Nigeria is that market.


